Needham Small Cap Growth Fund – 3Q26

Download PDF

Market Review & Macro Observations

  • Late July correction exposed fragility in AI hardware. A sharp market correction triggered the collapse of Situational Awareness, L.P., a $45 billion leveraged AI-focused hedge fund. The resulting forced selling hit technology hardware stocks that had led in the first half of 2026.
  • Rotation and dispersion beneath the surface. First-half winners saw profit-taking outflows as capital moved into industries that had not yet participated. Major indices masked the churn, and the bottlenecks that constrain long-term technology growth remain unchanged.
  • The Fed tightened, with more expected. The Federal Reserve raised rates a quarter point at its most recent meeting, and further increases are expected in 2026. The goal is to cool inflation expectations.
  • Energy and commodity costs keep inflation a significant risk. Oil is above $100[1] a barrel and diesel in the U.S. is well above $6.00[2] a gallon as of this writing. Steel, copper and aluminum prices add pressure, which will weigh on company margins and end customers. Rate hikes alone won’t lower global energy costs; and a resolution of the Middle East conflict would do the most to ease them.
  • Global funding conditions are shifting. The Yen required intervention to stabilize its decline, and the decades-old “carry trade” appears to be at an inflection point. Federal borrowing needs now face significant competition from corporate borrowers.
  • Consumers, housing and capital markets are under strain. Higher energy and food prices pressure consumer spending. Housing transactions are limited by higher mortgage rates and homeowners’ reluctance to give up low existing rates. Capital markets were strong early in the year but are slowing as large IPOs are postponed and the cost of capital rises, though M&A remains active.
 

Portfolio

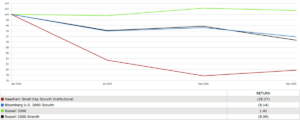
  • The Fund’s Institutional (NESIX) and Retail classes (NESGX) returned -20.27% and -20.35% respectively in the third quarter, compared to the Russell 2000 Growth’s -9.39% and the Russell 3000’s 1.41%. Year-to-date, the Fund’s Institutional (NESIX) and Retail classes (NESGX) returned 49.20% and 48.60%, compared to the Russell 2000 Growth’s 10.71% and the Russell 3000’s 12.42%.
  • We believe there is significant value within the small-cap asset class. Management teams continue to focus on improving cost structures and margins, accelerating revenue, expansionary planning and strengthening balance sheets.
  • The Fund ended the quarter with a 7.9% cash position.
  • The Fund’s top five performers in 3Q26 were: Netskope, Inc (NTSK), 908 Devices, Inc. (MASS), Lantronix, Inc. (LTRX), Super Micro Computer, Inc. (SMCI) and Unusual Machines, Inc. (UMAC).
  • The Fund’s top five detractors in 3Q26 were: Arteris, Inc. (AIP), Vishay Intertechnology, Inc. (VSH), nLight, Inc. (LASR), Harmonic, Inc. (HLIT) and Veeco instruments, Inc. (VECO).

Outlook

  • The micro picture is stronger than the macro sentiment. The market appears to be climbing a “wall of worry.” Oil volatility and restrictive rates keep sentiment cautious, but corporate fundamentals tell a more robust story, and domestic reindustrialization is moving forward.
  • Semiconductor manufacturing and capital equipment show the greatest strength. Revenue and earnings are growing despite valuation-multiple compression. Chip complexity is driving higher tool density per wafer, and immediate beneficiaries report order visibility through 2027 and into 2028, a level that veterans haven’t seen before.
  • AI demand should sustain capital investment. Agentic AI inference is just beginning, and enterprise and sovereign spending are broadening AI’s global reach. Cybersecurity will be critical, and predictions that AI will kill software companies look overblown, with technological moats separating winners from losers.
  • Data centers and power remain a long-term build-out with near-term headlines. Demand is not expected to slow for years. November midterm elections have made data centers a local political issue in multiple states, and that risk will likely persist after election season. Ultimately, we expect most projects to be built, with “Behind the Meter” power generation requiring substantial infrastructure investment.
  • Defense modernization and policy backdrop offer support, with risks to monitor. Military modernization is shifting to rapid ramp-ups in autonomous systems, drones and directed-energy weapons. A divided Washington may limit new policy uncertainty and let companies invest with more confidence. Key risks include rare earth supply constraints (China), tariff and trade negotiations, and geopolitical exposure around Taiwan.
  • Positioning favors quality. Investors should focus on companies with good balance sheets, strong management teams and boards, and technological moats that sustain long-term margins.

Definitions and Disclosures

The information presented in this commentary is not intended as personalized investment advice and does not constitute a recommendation to buy or sell a particular security or other investments. This message is not an offer of the Needham Growth Fund, the Needham Aggressive Growth Fund, or the Needham Small Cap Growth Fund (each a “Fund” and collectively, “the Funds”). Shares are sold only through the currently effective prospectus. Please read the prospectus carefully and consider the investment objectives, risks, and charges and expenses of the Fund carefully before you invest. The prospectus contains this and other information about the Fund.

All three of the Needham Funds have substantial exposure to small and micro-capitalized companies. Funds holding smaller-capitalized companies are subject to greater price fluctuation than those of larger companies. Needham Small Cap Growth Fund’s ownership as a percentage of net assets in the stated securities as of September 30, 2026: NTSK: 0.85%; MASS: 1.34%; LTRX: 2.32%; SMCI: 0.73%; UMAC: 2.18%; AIP: 7.04%; VSH: 6.55%; LASR: 3.46%; HLIT: 1.69%; VECO: 3.81%.

The Russell 3000® Index measures the performance of the largest 3,000 U.S. companies representing approximately 96% of the investable U.S. equity market, as of the most recent reconstitution. The Russell 3000 Index is constructed to provide a comprehensive, unbiased and stable barometer of the broad market and is completely reconstituted annually to ensure new and growing equities are included. The Russell 2000 Growth Index includes those Russell 2000 Index companies with higher price-to-value ratios and higher forecasted growth values. An investor cannot invest directly in an index. Needham & Company, LLC is a wholly owned subsidiary of The Needham Group, Inc. Needham & Company, LLC, member FINRA/SIPC, is the distributor of The Needham Funds, Inc.

The source of the data for each of the Russell 2000 Growth Index and the Russell 3000 Index (together, the “Indexes”) is the London Stock Exchange Group plc and its group undertakings (collectively, the “LSE Group”). © LSE Group 2026. All rights in the Indexes vest in the relevant LSE Group company which owns the Index. The Indexes are calculated by or on behalf of FTSE International Limited or its affiliate, agent or partner. Neither the LSE Group nor its
licensors accept any liability for any errors or omissions in the Indexes; no party may rely on the Index returns shown; and the LSE Group makes no claim, prediction, warranty or representation about the Fund or the suitability of the Indexes with respect to the Fund. No further distribution of data from the LSE Group is permitted without the relevant LSE Group company’s express written consent. The LSE Group is not connected to the Fund and does not promote, sponsor or endorse the Fund or the content of this prospectus.